At AFIS 2026 in Luanda, Angola, leaders from the International Finance Corporation, Jeune Afrique, and the Angolan authorities delivered a stark consensus: Africa’s monetary establishments are reserving document income, however till capital flows away from dollar-denominated debt and paper belongings into local-currency credit score, MSMEs, and infrastructure, continental progress will stay caught.
The central paradox of contemporary African finance was laid naked inside the plenary halls of the Africa Financial Summit (AFIS 2026) in Luanda: the continent’s banking trade has by no means been extra worthwhile, but the companies, infrastructure, and entrepreneurs driving real financial exercise have hardly ever felt extra starved of credit score.
Addressing a room of central financial institution governors, finance ministers, institutional buyers, and fintech executives, Amir Ben Yahmed, CEO of Jeune Afrique Media Group and co-founder of AFIS alongside the International Finance Corporation (IFC), framed the stakes in blunt phrases.
“Over the past two decades, Africa’s finance is stronger, but it still underfunds the real economy,” Ben Yahmed stated. “The question is no longer simply how to make African finance stronger. It’s how to make African finance matter more.”
That query defines this 12 months’s summit theme—“Making Capital Count: Unlocking Growth Through African Finance.”
The gathering marks the summit’s first foray into Southern Africa and the Lusophone world. Throughout the opening addresses, a transparent narrative emerged: with African banking revenues breaching $100 billion in 2024 and delivering returns on fairness rivalling the world’s most profitable rising markets, the monetary system can now not justify retreating behind risk-averse stability sheets whereas 85% of the continent’s workforce stays boxed into the casual economy.
The real-sector hunger: High returns, low credit score
Opening the summit, Angola’s Minister of State for Economic Coordination, Dr José de Lima Massano, took direct intention at the dislocation between monetary liquidity and real-sector productiveness.
Massano acknowledged that continental banking revenues are exhibiting encouraging indicators of business maturity. Yet, the transmission mechanism into business output stays jammed.
“We have increasingly profitable financial institutions on the continent, but credit to the private sector remains limited in many of our economies,” Massano identified. “Sectors such as agriculture, manufacturing, and small and medium-sized operators remain insufficiently financed.”
The consequence, Massano defined, is an financial mannequin working with one hand tied behind its again.
With roughly 85% of African employment concentrated in the casual economy, nationwide treasuries endure from an eroded tax base, whereas tens of millions of micro-entrepreneurs are robotically locked out of formal banking halls that demand classical bodily collateral.
Massano pressured that bridging this divide requires a radical shift in direction of digital finance and various underwriting fashions: “The digitalisation of financial services, including the use of solutions based on artificial intelligence, can help lower costs, create new risk-assessment instruments, and expand access to financial services for enterprises and citizens who lack the formal collateral conventionally demanded by the banking system.”
IFC’s mandate: De-dollarisation, fairness, and cash-flow underwriting
Taking the podium, Makhtar Diop, Managing Director of the International Finance Corporation (IFC), picked up the gauntlet.
Africa is presently increasing at an estimated 4.5% GDP progress charge, Diop famous, however that tempo is essentially inadequate to take up the tens of millions of younger individuals coming into the job market yearly.
To obtain structural transformation, the continent should speed up previous 6% progress—a feat that calls for a whole overhaul of how capital is deployed.
“Africa has capital. It has entrepreneurs. It has extraordinary talent,” Diop famous. “Our task is to connect these strengths through financial systems that can deliver on the continent’s ambitions. The conversations we have, the partnerships we forge, and the commitments we make over the next two days at AFIS will help determine whether African savings become the capital that builds African businesses, African infrastructure, and African jobs.”
For Diop, the continent’s capital mismatch is deeply structural: African corporations are choked by short-term, dollar-denominated debt whereas their revenues are earned totally in risky home currencies.
“African companies need more equity. We need more local currency. Borrowing in dollars creates a mismatch,” Diop argued, stressing that native capital markets should be mobilised to intermediate home pension and sovereign financial savings into real-economy belongings.
Diop outlined the operational shifts underway at the IFC below its 2030 technique, designed to dismantle these bottlenecks.
To handle aggressive local-currency financing, he famous that the IFC now executes 75% of its continental lending in native forex, thereby insulating debtors from foreign-exchange shocks.
According to him, having scaled up from mobilising $32 billion, the IFC is focusing on $100 billion in annual commitments, backed by a 3.4-to-1 mobilisation ratio, together with a $25 billion goal for risk-mitigating credit score ensures.
On Collateral-Free MSME Underwriting, Diop famous that the IFC was shifting away from land-title-heavy underwriting towards cash-flow and transaction-data lending, utilizing fintech rails and telematics to underwrite MSMEs based mostly on operational efficiency quite than immovable belongings.
The IFC can be reorganising its institutional footprint throughout monetary capitals—together with Tokyo, New York, and Sydney—to channel sovereign wealth funds and offshore pension swimming pools into African non-public fairness and infrastructure.
In Angola alone, Diop confirmed that he would signal two new agricultural financing agreements throughout his go to, advancing the continent’s meals safety agenda.
Above all, Diop cautioned in opposition to monetary engineering that loses sight of demographic realities: “The main reason we are mobilising resources in the financial sector is to create jobs. We need to focus totally and utterly on job creation for African youth.”
Angola’s ‘aggressive’ macro and monetary pivot
That AFIS 2026 is convening in Luanda is not any coincidence. Both Ben Yahmed and Diop pointed to Angola as a reside laboratory of macroeconomic stabilisation, fiscal restructuring, and capital-market revitalisation.
Sharing private reflections from his first skilled flight to Luanda many years in the past throughout a turbulent period, Ben Yahmed highlighted how Angola has dismantled its post-war structural handicaps to emerge as Africa’s sixth-largest economy, with an estimated nominal GDP of roughly $152 billion (and the third-largest in Sub-Saharan Africa, per April IMF projections).
Data introduced throughout the opening session mapped an aggressive transition from an oil-dependent petrostate into a diversified economy.
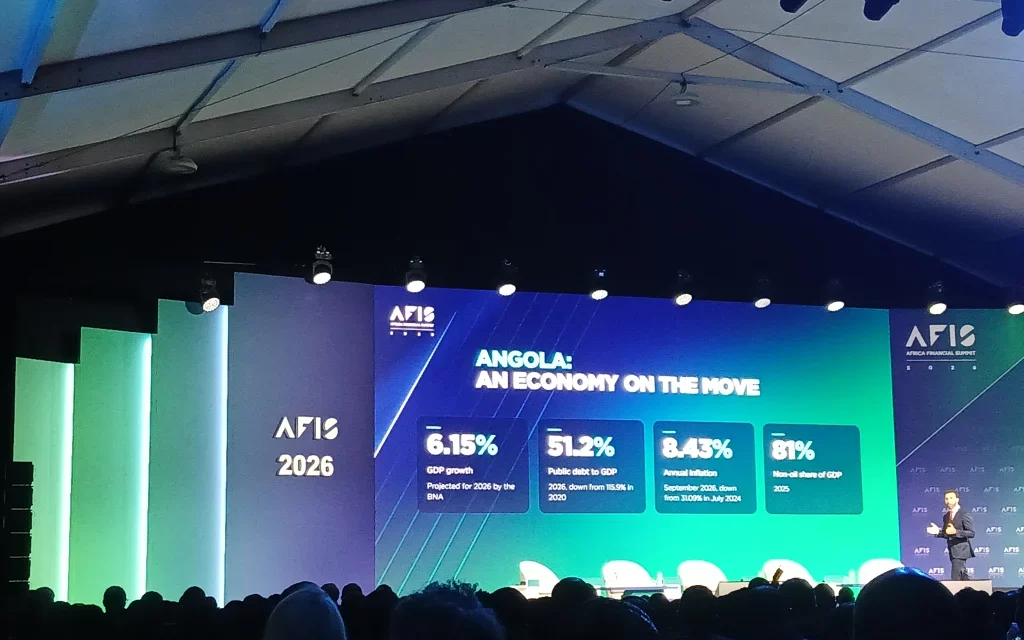
The Banco Nacional de Angola (BNA) initiatives 6.15% GDP progress for 2026. Notably, real GDP surged by 8.74% in Q2 2026, with the non-oil sector increasing by 9.24%.
Public debt as a share of GDP has collapsed from 115.9% in 2020 to 51.2% in 2026.
Headline inflation plummeted from 31.09% in July 2024 to 8.43% by September 2026.
The non-oil sector contributed 81% of GDP in 2025 (and presently instructions roughly 85% of the productive construction), with agriculture and livestock producing 23% of nationwide output.

The multi-billion-dollar Lobito Corridor—linking the mineral wealth of the DRC and Zambia straight to Angola’s Atlantic port—alongside nationwide rail modernisations and early green-hydrogen investments.
This structural macro cleanup has triggered an explosion in Angola’s home monetary sector.
Total banking belongings expanded 11.5% year-on-year to $28.2 billion in 2025, whereas sector web income reached an all-time document of $1.08 billion (+23%). Gross written insurance coverage premiums rose 21% to roughly $620 million.

On the capital markets entrance, the Luanda-based inventory alternate, BODIVA, noticed its market capitalisation skyrocket by 202% in 2025 to $4.3 billion, anchored by two historic preliminary public choices (IPOs): the September 2025 itemizing of Banco de Fomento Angola (BFA), which raised roughly $240 million, and the July 2026 itemizing of telecoms big Unitel, which raised $321 million—the largest fairness float in Angolan historical past.
Reflecting this renewed institutional confidence, Diop confirmed that the IFC’s funding portfolio in Angola has surged from lower than $150 million to over $1 billion in simply two years.

The new African monetary structure
Beyond nationwide stability sheets, the opening plenary drilled into the systemic integration required to create a friction-free inner market below the African Continental Free Trade Area (AfCFTA).
Minister Massano famous that prime cross-border settlement prices and regulatory fragmentation proceed to suppress intra-African commerce.
He urged business lenders and central banks to speed up the operationalisation of the Pan-African Payment and Settlement System (PAPSS) and advance the ongoing integration of continental inventory exchanges to enable cross-border capital mobilisation.
Ben Yahmed highlighted that the summit would highlight new institutional blueprints from the continent’s main growth establishments: Dr Sidi Ould Tah, President of the African Development Bank (AfDB), who will unveil a framework for a New African Financial Architecture for Development; George Elombi, President of Afreximbank; and Samaila Zubairu, CEO of the Africa Finance Corporation (AFC).
Drawing inspiration from Latin America’s digital banking evolution, Ben Yahmed pointed to Brazil’s Nubank—which grew from zero to develop into the nation’s second-largest monetary establishment in lower than 15 years—as a case research for African lenders navigating high-interest-rate environments and legacy department networks.
As delegates dispersed into closed-door bilateral periods and panel tracks, the mandate delivered from Luanda was unequivocal: balance-sheet well being with out real-economy impression is now not a viable benchmark for African finance.
The continent has collected the institutional heft, banking income, and sovereign sources to self-fund its growth.
The activity now could be engineering the home rails, fairness devices, and digital instruments needed to make that capital work for the tens of millions of younger Africans ready at the gate.