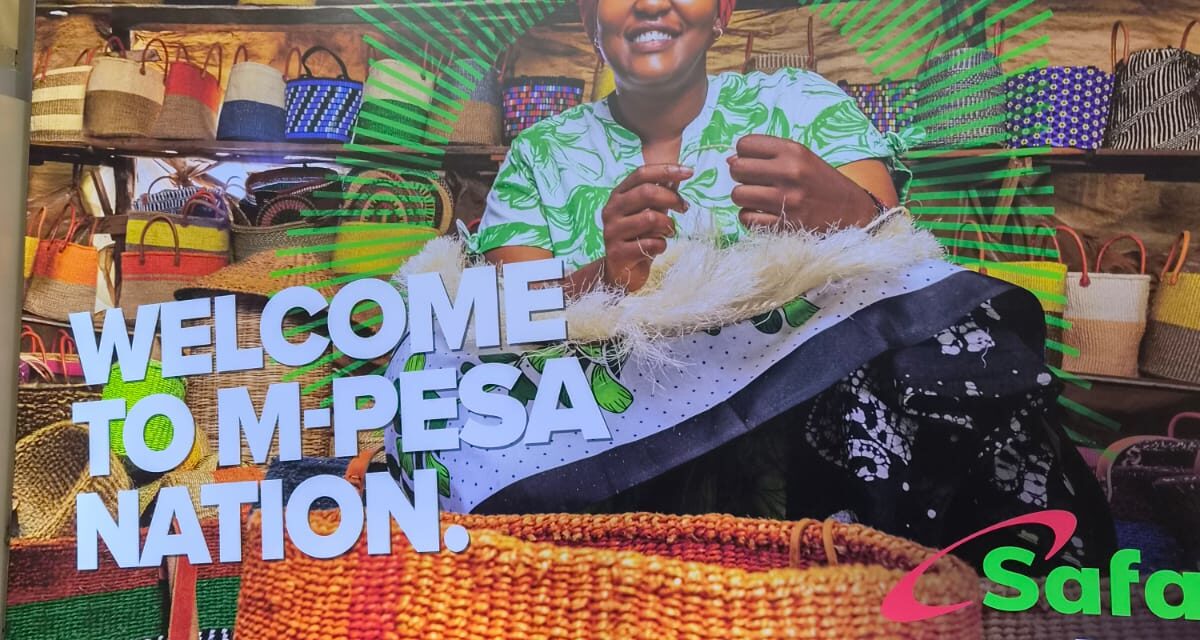
The following displays on practically 20 years of monetary inclusion by means of Kenyan-born M-Pesa.
When discussing the worldwide fintech revolution, consideration usually turns to Silicon Valley, London or Singapore. Yet one of the necessary monetary improvements of the previous twenty years got here from someplace very completely different: Kenya.
In 2007, Safaricom launched M-Pesa, permitting individuals to ship and obtain cash utilizing a primary cell phone. At the time, tens of millions of Kenyans lacked entry to conventional banking providers, significantly these dwelling exterior main city centres.
What adopted was greater than a technological innovation. M-Pesa essentially modified how atypical individuals interacted with cash.
Nearly 20 years later, its affect extends far past Kenya. From cellular funds in neighbouring African international locations to digital wallets throughout Asia and different rising markets, M-Pesa helped show that monetary inclusion didn’t essentially require a financial institution department, a traditional checking account or perhaps a smartphone.
Kenya’s transformation and Africa’s cellular cash revolution

Before M-Pesa, transferring cash between Nairobi and a rural neighborhood might contain travelling appreciable distances, counting on casual preparations or paying comparatively costly charges.
M-Pesa modified this by turning the cell phone right into a monetary software.
For many Kenyans, significantly these working in casual employment, small companies and agriculture, this supplied a sensible option to take part within the monetary system.
The impression has been vital. As highlighted in my earlier 2026 overview of Kenya’s fintech ecosystem for The Fintech Times, formal monetary entry has risen from roughly 26 per cent of adults in 2006 to round 85 per cent lately.
Whilst M-Pesa can not declare sole accountability, it has undoubtedly been central to this transformation.
It additionally helped set up Kenya as a number one African fintech hub, alongside Nigeria, South Africa and Egypt.
The wider significance is that Kenya demonstrated one thing different rising economies might be taught from: innovation doesn’t all the time must originate from the world’s wealthiest monetary centres.
In reality, the absence of intensive conventional banking infrastructure helped create the situations for a distinct method.
Similar developments subsequently emerged elsewhere in Africa, together with Ghana, Tanzania, Uganda and Senegal. As explored in my analysis of Senegal’s mobile money landscape, digital monetary providers are more and more changing into an entry level into the formal financial system.
In addition, M-Pesa could be argued has impressed innovation from past Africa equivalent to in Southeast Asia with the likes of GCash within the Philippines for example.
M-Pesa in 2026: Beyond sending and receiving cash

Fast ahead to 2026 and M-Pesa is now not merely a cash switch service. It has developed right into a broader monetary ecosystem encompassing service provider funds, financial savings, credit score, worldwide transfers and providers supporting companies.
According to Safaricom’s financial year 2026 results, M-Pesa income elevated by 13.4 per cent to KSh182.73billion, while its one-month energetic buyer base reached roughly 41 million.
These figures illustrate how deeply the platform has change into embedded in Kenya’s financial system.
Perhaps extra attention-grabbing is its enlargement into Ethiopia, Africa’s second-most-populous nation.
Safaricom Ethiopia reported that M-Pesa prospects greater than doubled to five.2 million throughout its 2026 monetary yr. This enlargement is necessary as a result of Ethiopia has traditionally had a extra restricted telecommunications and monetary providers surroundings.
Its expertise might show how elevated competitors and digital monetary infrastructure can speed up monetary inclusion in different markets.
However, challenges stay. Digital fraud, transaction prices, client safety and extreme borrowing by means of digital lending platforms elevate reputable considerations. Greater entry to credit score, for instance, doesn’t routinely translate into improved monetary wellbeing.
Kenya’s personal National Financial Inclusion Strategy 2025–2028 displays the significance of creating a extra inclusive and sustainable monetary ecosystem.
The subsequent chapter: From monetary entry to monetary empowerment

The international alternatives for cellular cash stay substantial. According to the GSMA‘s State of the Industry Report on Mobile Money 2026, there have been 2.3 billion registered cellular cash accounts worldwide final yr, with transactions exceeding $2trillion.
However, solely 593 million accounts had been energetic inside a 30-day interval. This highlights an necessary distinction between monetary entry and significant monetary participation.
The subsequent part of cellular cash ought to due to this fact deal with three areas.
First, increasing entry to financial savings, inexpensive credit score and insurance coverage, significantly for girls, rural communities and small companies.
Second, enhancing interoperability between banks, cellular wallets and worldwide fee techniques. For migrant staff sending remittances dwelling, cheaper and sooner cross-border funds might make a substantial distinction.
Third, strengthening client safety and digital monetary literacy. Financial inclusion means little if customers can not confidently and safely handle their cash.
Artificial intelligence (AI) might additionally help extra personalised monetary providers, though safeguards round information privateness and accountable lending might be important.
Ultimately, M-Pesa’s best achievement isn’t merely the billions of {dollars} transferring by means of its platform. It is {that a} resolution developed across the on a regular basis wants of Kenyans helped change how the world thinks about monetary providers.
As M-Pesa approaches its twentieth anniversary in 2027, the problem is now not proving that cellular cash works. It is guaranteeing that the following era of cellular cash innovation helps individuals do greater than switch cash: save, make investments, construct companies and enhance their financial prospects.
That could be a fair larger legacy for an innovation that started in Kenya.
AI degree 1 of 5: written by the contributor named within the piece; AI helped with tone, construction or wording; edited and signed off by Mark Walker, Editorial Director. What the levels mean