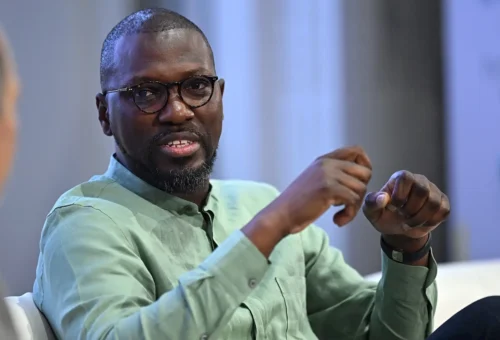
Nearly half of all gross mortgage advances within the UK through the second quarter of 2026 had been made to debtors at excessive loan-to-income ratios, in keeping with figures from the FCA and Bank of England. That share rose to 46% from 41.4% a yr earlier, a trajectory that Jinesh Vohra, chief govt and co-founder of mortgage overpayment platform Sprive, says indicators a structural drawback the business will not be adequately addressing.

Vohra made the remarks on the most recent episode of Twenty7tec‘s ELEVATE Podcast Series, in dialog with host Ellisha Jade. His central argument is that month-to-month affordability has grow to be the dominant body for mortgage selections, whereas the lifetime value of debt receives far much less consideration from lenders, brokers and debtors alike.
“I think it’s very important that people understand the cost of debt, because it’s not just about meeting the monthly payments,” Vohra stated. “You have to be able to do that over the entire lifetime of the mortgage.”
The structural shift in borrowing behaviour
The affordability squeeze has pushed a rising proportion of first-time consumers towards prolonged mortgage phrases of 30 or 40 years. A long run reduces the month-to-month fee and brings extra debtors inside a lender’s affordability calculation, however it considerably will increase the entire curiosity paid and leaves debtors carrying materials debt later into their working lives and, in some instances, into retirement. Research from Yorkshire Building Society cited within the launch discovered that 56% of potential first-time consumers nonetheless take into account mortgage acceptance troublesome, which suggests the underlying affordability constraint has not eased regardless of the structural workarounds now in widespread use.
Compounding that is the sample of intermittent buyer engagement that characterises a lot of the adviser market. Twenty7tec’s personal August 2026 Mortgage Market Snapshot recorded 616,150 remortgage searches, a rise of 11% yr on yr. That exercise displays debtors actively reviewing their preparations, however Vohra argued that two-to-five-year remortgage cycles aren’t ample to supply the continuing monetary help householders want.
“If you are interacting with that customer every two to five years, when they’re effectively looking to refinance, how strong is that relationship?” he stated.
Regulatory and market context
The rising share of excessive loan-to-income lending will not be new to regulators. The Bank of England’s Financial Policy Committee has maintained a circulate restrict on excessive loan-to-income mortgage lending since 2014, capping at 15% the proportion of new lending at or above 4.5 instances revenue for any given lender. The Q2 2026 information level of 46% refers back to the broader excessive loan-to-income bracket, not solely these at or above 4.5 instances, however the directional development has attracted regulatory consideration as affordability strain intensifies. Any vital deterioration in borrower resilience at prolonged phrases may immediate the FCA or PRA to revisit the adequacy of affordability stress assessments.
Sprive’s personal place is that expertise and information can help extra steady borrower engagement exterior of transaction moments. The platform permits householders to direct spending rewards towards mortgage overpayments and offers modelling instruments on the influence of early reimbursement. Vohra’s Series A, a $10 million spherical introduced in September 2026 and bringing complete funding to greater than $15 million, is earmarked for buyer acquisition and income development within the UK market. The industrial thesis rests on sustained buyer relationships reasonably than point-in-time origination, which aligns the product with the structural critique Vohra is making of the broader business.
For mortgage expertise suppliers and lenders, the talk factors to a rising industrial alternative in post-origination engagement instruments, an space the place the business’s present expertise stack, constructed largely round sourcing and utility processing, stays comparatively skinny.
AI degree 1 of 5: written by Darlyn Ho; AI helped with tone, construction or wording; edited and signed off by Mark Walker, Editorial Director. What the levels mean