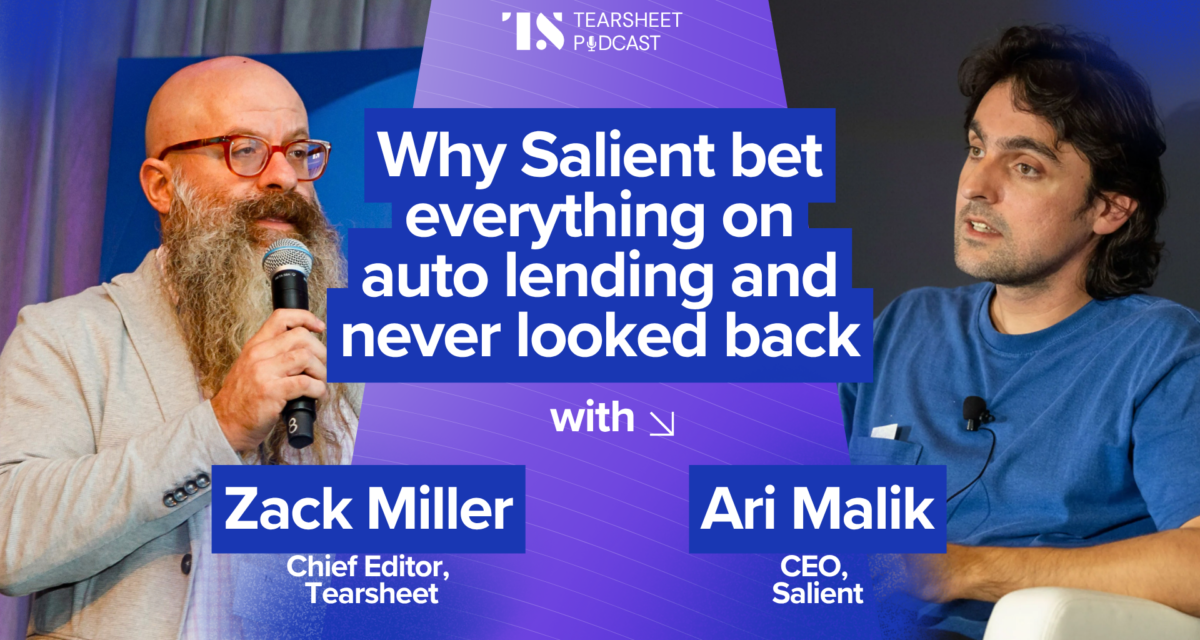
Most AI startups chase breadth. They construct a succesful, general-purpose product and promote it throughout as many industries as are keen to purchase it. Ari Malik, CEO of Salient, took the alternative strategy. He picked one vertical, auto lending, and went deep sufficient that he finally moved his firm’s headquarters to Los Angeles to be nearer to a single buyer, Westlake Financial.
Two years later, Salient is dwell inside roughly half of the highest 20 auto lenders within the nation. By Malik’s account, the corporate has never misplaced one. In in the present day’s episode, he walks us by how a call that “wasn’t really ideological” became a full-stack servicing layer now dealing with collections, complete loss, compliance, and loss restoration for a number of the largest lenders within the U.S.
The origin story is much less a strategic plan than lived expertise. Malik got here to the issue by the finance facet of a previous firm, Tesla, the place he bought an in depth take a look at how tangled mortgage servicing had change into. “The workflows in this hyper-regulated part of the economy were so tangled with compliance obligations, state-specific regulations, legacy systems that weren’t API-friendly or real-time,” he stated, “that we sort of felt like you could build something generic and horizontal, and actually have it work.”
Malik’s conviction has solely hardened as horizontal AI instruments have tried to maneuver into client lending and run headlong into compliance violations. For Malik, the learn was easy: a market this huge and this regulated was ripe for going deep.
Watch the episode
Listen to the complete podcast
Subscribe: Apple Podcasts I SoundCloud I Spotify
Read the entire transcript (for TS Pro subscribers)
Depth over breadth, by necessity
Salient’s vertical bet rests on two observations: the regulatory complexity of auto lending makes horizontal instruments brittle, whereas the market itself is gigantic. Roughly $800 billion in new U.S. auto debt is issued yearly, backed by a military of human brokers making calls, sending letters, and negotiating funds. “It was a structural problem that was sitting at the largest asset classes, right, and across the largest lenders in the U.S.,” Malik stated.
The incumbent different, in his telling, was servicing dealt with by BPOs with little visibility and vital compliance publicity. That left room for “an excellent software solution” to compete on belief as a lot as effectivity. Malik is candid that there was no grand plan behind any of this – only a panorama that pointed towards one massive, underserved drawback fairly than many small ones.
That considering additionally drove Salient’s resolution to relocate to Los Angeles and be in nearer proximity to Westlake Financial. Malik calls it “probably the most important thing we’ve ever done as a company.” Working alongside Westlake’s compliance, servicing, and total-loss groups surfaced nuances that may have been invisible from a distance. “What we think is extraordinarily intuitive may not be for the customer,” he stated.
AI maturity is touchdown inconsistently throughout lenders
Malik gently pushed back on the idea that client lending remains to be caught on the “is this real?” stage of AI adoption. Two years in the past, he stated, that doubt was real. Salient reportedly ran a demo on the time, wherein an AI-generated voice of “Steve Jobs” referred to as lenders, and the response was disbelief that the decision wasn’t prerecorded. That skepticism has largely pale, however inconsistently.
Bulge-bracket banks, considerably counterintuitively, have moved quickest. Malik described enterprise-grade lenders as “extraordinary fast adopters of deploying AI not only in a consumer-facing way but also at the back end on the workflow side, where they can accrue more value.” Mid-market lenders and fintechs, in contrast, have been extra hesitant, which he attributes to having much less publicity to the associated fee and regulatory pressures pushing bigger establishments to behave.
The pitch has modified accordingly. Where the early dialog was about threat (what occurs if the AI says one thing incorrect), the argument now, backed by information from the most important deployments, is that AI may be safer and extra compliant than a human workforce, with measurable enhancements in roll charges. This reframing, Malik stated, “hasn’t really percolated down fully yet to the smaller fintech.”
A product stack constructed by buyer pull
Salient began with Taylor, a voice agent dealing with collections, servicing, and total-loss calls. The remainder of the stack, Malik stated, got here from lenders pulling the corporate deeper into their workflows fairly than from an inside roadmap. Calls that appeared resolved on the floor saved spawning downstream work: a credit score dispute or chargeback that bought routed to a human queue and sat there for 2 weeks. “We were like, this is taking two weeks. Why is this taking so long? We should resolve this with the customer,” Malik stated. So Salient constructed that piece too.
Marshall, the corporate’s compliance and QA product, emerged the identical manner. As Salient’s consumer-facing instruments scaled inside regulated establishments, lenders began asking how you can show the AI itself was compliant: audit trails, mannequin threat documentation, and system-of-record checks. Rather than lenders hiring extra employees to police the brand new expertise, Malik stated the response was to “create this product called Marshall, and it will automate compliance monitoring, QA monitoring, checking the system of record, cleaning it up, and outputting almost an audit report that can go to regulators.”
From there, the suite expanded into complete loss, credit-card chargebacks, and charge-offs, each a response to a selected ache level fairly than a characteristic added for its personal sake.
Selling threat to banks, effectivity to everybody else
The gross sales dialog, Malik stated, modifications totally relying on who’s shopping for. Mid-market and non-bank lenders reply to effectivity: deal with time, working bills, restoration {dollars}, and scalability. Bulge-bracket banks are a special animal totally, involving a steering committee, a compliance staff, a vendor threat staff, IT safety, and authorized overview. “I had a lot more hair before we started navigating through bulge-bracket banks,” he joked.
With that viewers, the true dialog is about threat discount, model-risk documentation below frameworks like SR 11-7, and satisfying regulators such because the OCC.
Notably, Salient doesn’t have a devoted gross sales staff. Malik stated primarily each buyer has come by referrals, and he stays personally concerned in each massive enterprise relationship, checking in with prospects weekly or month-to-month. He describes the sign {that a} lender has really purchased in not as a single second however as a change in tone: the query stops being whether or not Salient can do one thing and turns into when. “That kind of shows that they’ve internalized this daily as part of their almost key operating model, rather than a pilot that’s constantly being run,” he stated.
The clearest proof of that mannequin working is Westlake, which set Salient a goal of $15 million in annual financial savings. Deploying the expertise throughout collections, complete loss, and compliance didn’t simply reduce prices. Average deal with time dropped, compliance violations dropped, and findings dropped alongside them. Malik stated Salient’s mapping of Westlake’s buyer interactions discovered that roughly 80% of use instances could possibly be dealt with totally by AI, releasing human brokers for instances that really require judgment.
The pitch, as he frames it, moved “from just being this weird, fun toy or experiment of generative AI… into a service quality story, into a risk mitigation story.”
What the business remains to be underestimating
Malik sees the largest alternative in making loss restoration predictive and individualized. Historically, remedy has been bucketed by easy delinquency guidelines fairly than who a buyer really is. His instance: two prospects every miss two funds within the final 60 days, one with a poor fee historical past and the opposite who has never missed a fee. Under most present techniques, they’re handled identically. Malik needs restoration selections to replicate these variations, retaining good prospects with the model by a tough stretch fairly than pushing them out over one short-lived information level.
Looking forward, Salient plans to launch three new merchandise by the top of 2026, with Malik much less concerned within the day-to-day than he was within the firm’s earlier years. “We’d really like to do it without me being super in the weeds on day one, but trusting my team to do more of it,” he stated.
It’s a becoming subsequent step for a founder who has spent two years arguing that the best way to serve a fragmented, regulated business effectively is to get shut sufficient to grasp it fully, then construct exactly for what you discover.