Every $10 (₦13,329.7) borrowed from OPay generated $2.55 (₦3,399.07) in loan-financing income in H1 2026. The determine consists of late-payment penalties, not simply curiosity, and presents a glimpse into the income lenders must cowl the chance of borrower defaults.
The fintech generated $236.12 million from $927.6 million in loans originated in Nigeria, in keeping with its public offering prospectus. But OPay put aside $118.36 million for anticipated credit score losses, equal to $1.28 (₦1,706.20) for each $10 lent. After provisions, roughly $1.27 (₦1,692.87) remained from each $10 lent.
Loan-financing income was equal to 25.5% of originations, towards the Central Bank of Nigeria’s 26.5% benchmark rate of interest throughout the interval. OPay’s determine will not be the rate of interest charged to particular person debtors, as income consists of accrued curiosity and penalties for late repayments.
On a ₦280,000 ($210.06) mortgage by means of the OPay app, TechCabal was provided 0% curiosity for a 15-day compensation interval, 18.3% for 30 days, and 16.8% for 60 days. The charges apply to all the compensation interval, not yearly.

The fintech’s determine presents a glimpse into the economics of digital credit score in Nigeria’s client lending market, estimated to be price $2.1 billion. Lenders should worth loans to cowl defaults, funding and working prices, with debtors who repay on time probably bearing a part of the price of lending to those that don’t.
The firm classifies loans which can be 90 days overdue as non-performing and expenses them off at 120 days overdue. Recoveries on beforehand written-off loans cut back credit-loss expense.
Nigeria’s standard banking framework classifies loans as non-performing after 90 days overdue, doubtful after 180 days, and as losses after 360 days. OPay reported an NPL ratio of 4.3% as of June 30, 2026, in contrast with 8.03% for the banking trade, above the prudential threshold of 5%.
But OPay’s 120-day charge-off coverage complicates comparisons with banks that classify loans as losses after 360 days. Loans OPay writes off may stay on a financial institution’s books for one more eight months, probably making OPay’s NPL ratio seem decrease. The firm doesn’t disclose the worth of loans charged off between these thresholds, making it unimaginable to estimate what its ratio can be beneath a 360-day timeline.
The economics of OPay’s lending
Lending is OPay’s largest income stream, producing 55.29% extra income than its next-largest enterprise. But anticipated credit score losses are rising sooner than lending income.
In H1 2026, it originated $927.6 million in loans, greater than 3 times the $305.1 million it originated a yr earlier. Loan-financing income grew 167.9% year-on-year to $236.12 million, whereas provisions for anticipated credit score losses elevated by 210.3%.
Provisions consumed 50.2% of loan-financing income in H1 2026, up from 41.0% a yr earlier. For each $10 OPay earned from lending, it put aside $5.02 to cowl anticipated credit score losses, leaving much less income to cowl different prices. The fintech is betting that an growing shift in the direction of service provider loans will cut back its credit score danger profile over time.
Illustrative Lending Revenue ()
Provision (50.1%)
Remaining (49.9%)
Illustrative Lending Revenue
$2.55
Expected Credit-Loss Provisions
-$1.28
Revenue Remaining (earlier than different prices)
$1.27
On a hypothetical $10.00 mortgage origination, the illustrative lending income is $2.55. OPay information $1.28 in anticipated credit-loss provisions, leaving $1.27 in income remaining earlier than funding, working, taxes, and different prices.
OPay units rates of interest based mostly on debtors’ profiles and danger assessments. Its loan-financing income contains curiosity accrued over the mortgage time period utilizing the efficient curiosity methodology, alongside penalties for late instalment funds. Provisions, nonetheless, are estimates of anticipated losses, not the ultimate quantity the corporate will fail to recuperate. Actual losses will depend upon defaults, subsequent recoveries, and adjustments in these estimates.
OPay has a considerable pool of money to fund its lending. As of June 30, 2026, it held $918.7 million in money, money equivalents, and short-term investments. “As of June 30, 2026, we did not have credit facilities provided by financial institutions,” the corporate mentioned in its prospectus.
OPay expects the proceeds from its public providing and concurrent non-public placement, along with present money and anticipated working money flows, to cowl its money wants for the subsequent 12 months.
OPay’s artwork of lending
OPay’s loans usually final round 100 days. The firm makes use of transaction knowledge to evaluate debtors who could lack standard credit score information. In 2025, fintech unicorn Moniepoint disbursed ₦1 trillion ($750.20 million) in loans utilizing transaction knowledge.
OPay mentioned its month-to-month energetic customers made a mean of 209 pockets funds a month. It has leveraged greater than 200 billion credit score and monetary knowledge factors and practically 50 billion behavioural knowledge factors to evaluate debtors, combining transaction histories with credit score information, revenue knowledge and third-party sources.
The firm runs greater than 5,000 machine-learning fashions and variants to evaluate creditworthiness, set mortgage limits, worth loans and monitor delinquency. Its fashions draw on gadget intelligence, transaction patterns, social graphs and user-consented monetary SMS knowledge. AI instruments additionally assist collections: WhatsApp reminders improved restoration charges by 3.5% in Indonesia, with rollout to Nigeria underway. OPay warns that poor knowledge, altering borrower behaviour, fraud and mannequin drift can weaken its predictions and enhance credit score losses.
The technique is scaling. OPay originated $1.56 billion in loans in Nigeria in the 12 months to June 30, 2026, and quarterly distinctive debtors reached 6.7 million in Q2 2026, greater than seven instances the quantity in Q1 2024.
Loan financing accounted for 50.55% of OPay’s $467.06 million in whole revenue in H1 2026. The firm additionally reported $90.87 million in working revenue.
OPay’s lending enterprise stays small relative to established Nigerian banks. Guaranty Trust Holding Company (GTCO), for example, reported a mortgage ebook of ₦3.14 trillion ($2.36 billion) in 2025. The figures aren’t instantly comparable: the 2 companies function at totally different scales, and their lending fashions differ
OPay can be increasing into new lending merchandise. It launched a purchase now, pay later (BNPL) product in September 2025 and disbursed $99 million in service provider loans and $5 million by means of the BNPL product. Merchant lending may assist OPay handle credit score danger as a result of common enterprise transactions present observable indicators of compensation capability.
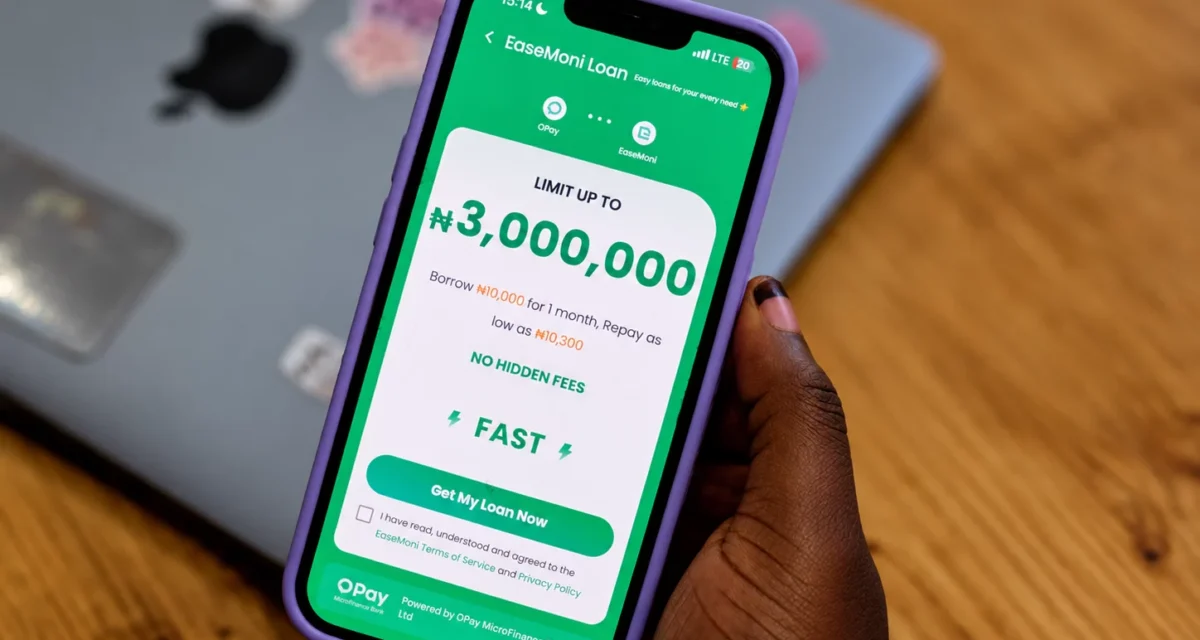
But as OPay expands its lending enterprise, it should additionally deal with the advertising techniques used to draw and recuperate loans. Selling and advertising bills rose 104.67% to $78.68 million in H1 2026. A TechCabal report in April 2026 recognized OPay, EaseMoni, and OKash (each tied to OPay) as main sources of complaints about harassment from digital lenders, together with persistent calls.
OPay reported a buyer acquisition price (CAC) of $1.90 in H1 2026, with common month-to-month income per consumer at $1.70 in Q2 2026.
In its prospectus, OPay says it limits advertising contact to twice per week and presents distressed debtors counselling, cost deferrals and penalty or curiosity waivers.
True scale calls for shifting past surface-level integrations to strong execution. We’ve filtered the noise out of Moonshot 2026, optimising the convention strictly for high-calibre connections between startup founders, international monetary operators, enterprise leaders and people rewiring Africa’s technical frameworks.
Get 20% off Early Bird tickets for a limited time.