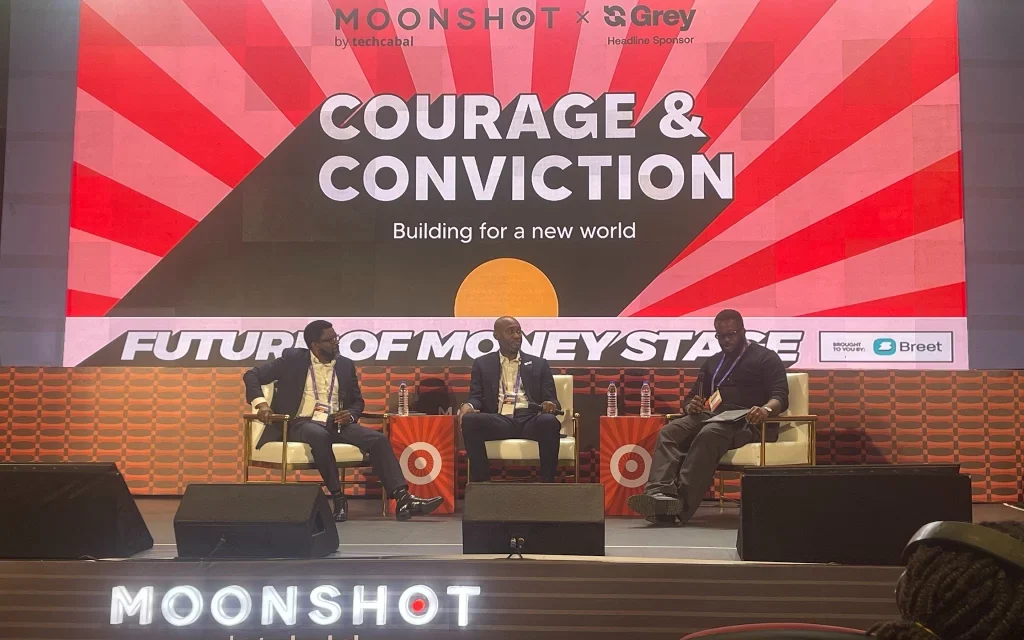
Banks must anticipate clients’ wants and embed monetary providers into on a regular basis transactions to compete with digital platforms, executives from Access Holdings and OPay instructed Moonshot by TechCabal in Lagos.
Daniel Awe, head of Fintech Foundry at Access Holdings, mentioned banking’s subsequent part would require establishments to provide providers when clients wanted them, relatively than await individuals to go to a department or open an utility.
“The future of banks is going to be in everyday people, where banks become invisible,” he mentioned throughout a panel titled “The Next Bank: Competing in the Age of Programmable Money”.
His argument extends the shift from department banking to cellular providers. Moving a transaction onto a cellphone adjustments how clients entry a financial institution; integrating finance into actions corresponding to paying college charges or replenishing inventory adjustments once they encounter it.
“When the customer is engaging you, it’s not the future of banking. It’s the banks that now have to place themselves in the life of the customer,” Awe mentioned.
Chukwudinma Okafor, chief compliance officer at OPay Nigeria, mentioned the start line needs to be clients’ sensible wants, relatively than the provision of recent know-how.
“For us at OPay, the major focus is just to address one thing, and that’s customers. You have to meet the customers where they need you,” he mentioned.
OPay despatched builders, know-how professionals and gross sales groups to markets throughout Nigeria to observe how merchants labored and collect suggestions, Okafor mentioned. Requests for various sounds to sign profitable and failed point-of-sale transactions illustrated how small adjustments may make a service extra helpful.
The instance highlighted a distinction in the dialogue: anticipating clients’ wants can contain subtle infrastructure, however the enchancment clients worth could also be simple.
Modernising the programs
Awe mentioned conventional banks would additionally want to overhaul the infrastructure supporting their merchandise. Conventional core banking programs alone have been inadequate for competing with fintechs and know-how firms providing monetary providers.
That transition would have to be gradual, preserving reliability and compliance whereas addressing the dangers created by more and more interconnected programs.
“Whatever you want to achieve, you have to put security in the middle,” he mentioned.
Okafor mentioned digital-first firms had benefited from beginning with extra fashionable infrastructure, together with cloud-based programs, whereas established banks have been more and more adopting comparable applied sciences.
Despite their competitors for patrons, each audio system argued that banks and fintechs remained depending on each other.
Awe mentioned partnerships mixed banks’ monetary capabilities with fintechs’ potential to serve specific buyer teams. Some companies required approaches that firms corresponding to OPay may present extra readily, he added.
Okafor pointed to fintechs’ reliance on business banks for settlement and the dealing with of buyer funds. Cooperation was additionally mandatory to reply to fraud when cash moved between establishments.
“Ultimately, we need each other for the ecosystem to work well,” he mentioned.
The dialogue additionally turned to Nigeria’s method to cryptocurrency and stablecoins, with Awe describing differing priorities amongst regulators.
He mentioned the Securities and Exchange Commission had proven higher urge for food for cryptocurrency-related actions, whereas the Central Bank of Nigeria had been extra cautious due to financial coverage and shopper safety considerations.
According to Awe, the central financial institution was inspecting stablecoin use circumstances by means of a regulatory sandbox, permitting authorized individuals to check providers underneath supervision.
He characterised stablecoins as much less risky than different cryptocurrencies. That distinction was his evaluation of their enchantment to the regulator, relatively than a assure of their stability.
For banks weighing new applied sciences, the broader problem recognized by the panel was to make providers simpler to entry whereas sustaining the safety and reliability clients anticipated. Becoming much less seen in a transaction would require substantial work on the programs behind it.