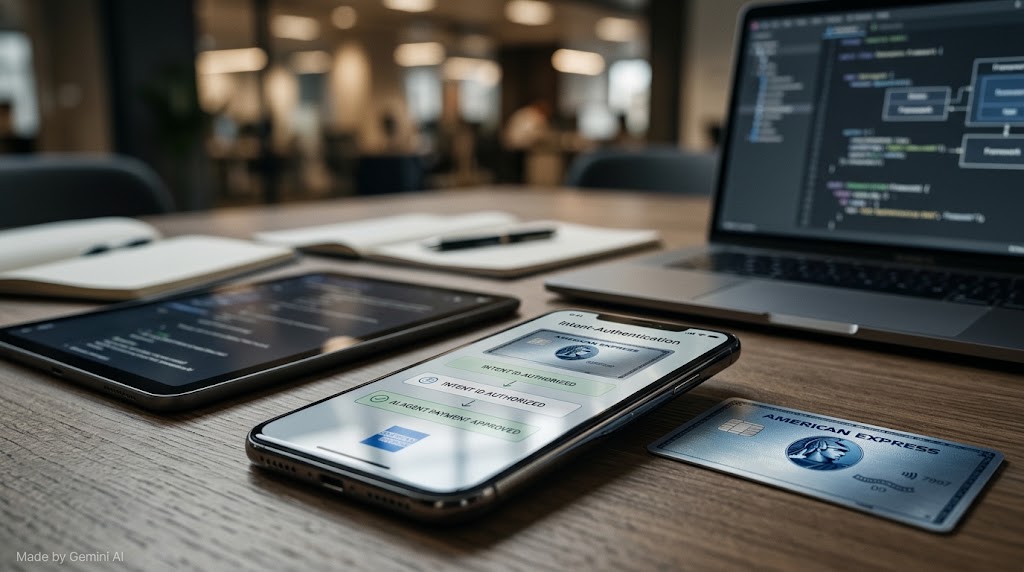
American Express revealed its Intent Intelligence framework on 13 October, setting out the technical specification for recording, authenticating and transmitting what a buyer instructed an AI agent to buy earlier than any cost is processed. The transfer makes Amex the primary main card community to publish detailed plumbing for agentic commerce, and it has direct implications for how legal responsibility will likely be allotted throughout the funds stack as autonomous buying brokers proliferate.
How the framework works

The structure centres on a Create Intent API that captures a buyer’s directions and constraints, masking the service provider, a most funds and different preferences. The buyer then authenticates and indicators off on what the agent recorded. Amex points an Intent ID and a Proof of Intent Token encoding these high-level constraints. The agent exchanges the token for a scoped cost credential used at checkout in place of the particular card quantity, and the Intent ID and token journey with the transaction by way of authorisation, fraud decisioning and any subsequent dispute course of.
Hannah Bozian, Amex’s VP of agentic partnerships and technique, described the rationale to TechCrunch as pulling intent earlier into the transaction circulation in order that threat is assessed earlier than a cost lands somewhat than after. Her illustrative instance: a buyer instructs an agent to purchase white Nike trainers in a measurement 9, the agent makes an attempt to buy Adidas as a substitute, and Amex can block the transaction on the level of credential validation.
The framework extends commitments Amex made in April when it launched its ACE developer equipment and Agent Purchase Protection, below which eligible cardholders who authorise an agent and cross authenticated intent to Amex can be protected against prices attributable to agent error. The April launch described that safety as a future dedication with phrases nonetheless to be finalised, and two of the equipment’s 5 companies remained in growth at that time.
Market context and regulatory read-across
Amex can transfer rapidly right here as a result of it operates a closed-loop mannequin as issuer, community and acquirer concurrently, giving it end-to-end visibility over a transaction {that a} four-party scheme can not replicate with out coordination throughout a number of counterparties. That identical four-party problem is being addressed at an trade degree by way of EMVCo‘s draft Intent Services framework, whose public remark window closed on 30 September, and thru a voluntary rules paper revealed final month by a bunch of six world banks together with Bank of America.
The route of journey throughout all three workstreams is constant: legal responsibility will observe whoever holds an authenticated, signed document of what the shopper truly authorised. That creates an instantaneous sensible query for issuers and processors working on Visa and Mastercard rails. Any financial institution or processor whose agent companions can not seize, cryptographically signal and cross intent knowledge by way of the authorisation chain will discover itself in a weaker dispute place as agentic transactions scale.
The regulatory body continues to be forming. Neither the FCA nor the Payment Systems Regulator has but issued particular steerage on AI agent transactions, although the PSR’s present authorised push cost fraud reimbursement guidelines place vital weight on whether or not a payer gave real, knowledgeable consent. An authenticated intent document of the type Amex describes can be a compelling artefact in that context. European regulators working by way of PSD3 implementation will face the identical definitional query: at what level does an agent’s motion represent the shopper’s consent?
For retailers, a cost credential scoped to a selected intent represents a meaningfully stronger dispute place than a saved card quantity submitted by an automatic course of. The industrial incentive to just accept intent-scoped credentials is actual, and acquirers might want to resolve how rapidly they construct the acceptance infrastructure.
AI degree 1 of 5: written by Darlyn Ho; AI helped with tone, construction or wording; edited and signed off by Mark Walker, Editorial Director. What the levels mean