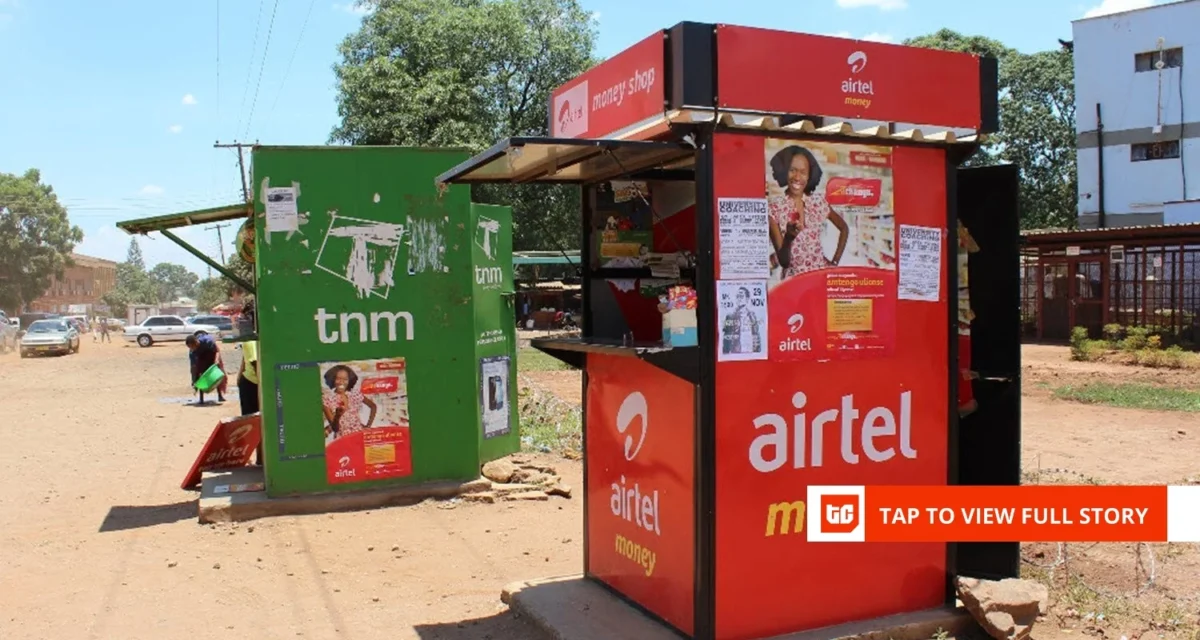
Airtel Mobile Commerce N.V., the Netherlands-based fintech arm of Airtel Africa, plans to launch a virtual cost card in Kenya, organising a brand new contest with Safaricom over worldwide online spending.
Developed with Mastercard, the Virtual Card Number (VCN) will combine with Airtel Money wallets, enabling prospects to pay for companies on international platforms resembling Amazon and Netflix with no conventional checking account.
The launch places Airtel Money Global Pay in direct competitors with M-PESA GlobalPay, Safaricom’s virtual Visa card introduced in 2022. Airtel is getting into a market the place Safaricom has a longtime lead, however the contest is about greater than the cost networks behind the playing cards. It additionally issues how prospects fund transactions, handle online spending, and entry credit score when their pockets balances run low.
The M-PESA GlobalPay card can draw on Fuliza, an overdraft facility that lets eligible prospects full online payments when their M-PESA steadiness is inadequate. Airtel Money’s pay as you go card lacks this function, requiring prospects to fund it earlier than making a purchase order.
Data from the Communications Authority of Kenya reveals M-PESA’s cellular cash market share has slipped to 88.8% in June 2026, down from almost 95% in 2023. Airtel Money’s share rose to 11.1% over the identical interval. The figures point out a gradual shift within the aggressive steadiness, though Safaricom’s lead stays substantial.
Global commerce presents a brand new income stream
Kenya’s rising use of digital companies offers each operators a purpose to compete for worldwide payments. Streaming subscriptions, software program companies, and abroad e-commerce platforms permit cellular cash suppliers to achieve spending that may in any other case movement by financial institution playing cards.
Netflix, which entered Africa in 2016, is one instance of how worldwide digital companies have develop into a part of on a regular basis spending. Virtual playing cards let prospects with out financial institution accounts pay these retailers by way of cellular cash, extending wallets’ attain past home transfers and service provider payments.
For operators dealing with stress on home cost costs, cross-border transactions additionally provide a option to earn income from worldwide commerce. Foreign forex conversion and service provider payments can generate earnings past the core enterprise of shifting cash between native accounts.
Safaricom’s international payments operation, which incorporates cross-border transfers, virtual playing cards, and app retailer billing, generated KES 4.76 billion ($37.2 million) within the financial year ended March 2026, up 22.3% from the earlier 12 months. M-PESA generated KES 182.7 billion (323.1 billion) in transaction worth throughout 46.4 billion transactions.
The figures present why even a comparatively small slice of M-PESA’s enterprise is essential. Global payments can contribute to income progress with out requiring Safaricom to win a comparable share of Kenya’s home cellular cash market. The alternative for Airtel is to seize a portion of that spending as extra prospects use its pockets for online purchases.
Across 14 African markets, Airtel’s cellular cash operation generated $1.3 billion in revenue, up from $747 million. The firm has issued more than 875,000 virtual cards in Uganda, Zambia and Tanzania since 2025 and plans to introduce the service in Kenya, the Democratic Republic of Congo and Gabon.
Credit and safety separate the playing cards
The two merchandise take totally different approaches to funding online payments. M-PESA GlobalPay hyperlinks to the shopper’s M-PESA pockets. In distinction, Airtel’s VCN mannequin requires prospects to switch funds from their predominant Airtel Money pockets to the virtual card earlier than making a purchase order.
The setup lets Airtel prospects ring-fence cash for online purchases, holding the remainder of their pockets steadiness separate from card transactions. It additionally offers them larger management over subscription payments and their online spending.
Customers nonetheless want to guard their account credentials and monitor transactions. The extent of safety additionally relies upon on the controls accessible to freeze or handle the card, to dispute unauthorised payments, and to stop additional costs.
Safaricom’s authentic virtual Visa card design used a card verification worth (CVV) that prospects generated by the M-PESA app after getting into their PIN. Each code lasted half-hour and might be used solely as soon as, limiting the window during which it might be used if uncovered.
Safaricom introduced the overdraft possibility for GlobalPay in 2026, permitting eligible prospects to finish online payments when their pockets steadiness is inadequate. The function may help forestall subscription payments from failing, but it surely additionally means automated costs could draw on credit score, leaving prospects with an overdraft to repay.
Airtel’s pay as you go mannequin doesn’t provide an equal overdraft facility, so prospects should have enough funds on the virtual card to finish a purchase order. This could also be much less handy, but it surely additionally prevents the card from extending spending by an equal credit score line.
A challenger nonetheless faces a scale downside
Safaricom’s massive buyer base offers GlobalPay a longtime viewers, whereas familiarity with M-PESA could make prospects much less inclined to modify cost strategies.
Airtel’s card might attraction to prospects who already use Airtel Money and desire a direct path to worldwide retailers. Its regional rollout additionally offers the corporate expertise to attract on because it enters the Kenyan market.
Customers will want to match international change costs, transaction limits, acceptance charges, dispute dealing with and the convenience of managing card particulars. Airtel’s pricing will be significantly essential as a result of a lower-cost card might appeal to price-sensitive customers, whereas unclear charges might blunt the attraction of its pay as you go design.
Airtel has but to reveal all the main points Kenyan prospects will have to assess the service, together with its international change costs. Safaricom’s GlobalPay applies a international change markup, making the whole value of a purchase order a related level of comparability.
The launch will not erase Safaricom’s lead in cellular cash. Still, it will give Airtel one other option to compete for buyer spending, this time on the online checkout moderately than by home transfers.
True scale calls for shifting past surface-level integrations to sturdy execution. We’ve filtered the noise out of Moonshot 2026, optimising the convention strictly for high-calibre connections between startup founders, international monetary operators, enterprise leaders and people rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.