Circle Gas, the UK father or mother of Kenyan pay-as-you-cook liquefied petroleum gasoline (LPG) provider M-Gas, reported $67 million in contracted carbon credit awaiting supply and $57 million in money prepayments in 2025, in line with its monetary statements.
The firm’s dependence on carbon-credit income exposes the monetary dangers dealing with Kenya’s clean-cooking companies, the place authorities authorisation can decide whether or not contracted credit ship their anticipated worth.
The firm’s accounts, filed in September, present the monetary stakes. Circle Gas misplaced $39.3 million in 2025, held $1.1 million in money at year-end and reported internet liabilities of $156.7 million. It wants about $28 million in new funding to finance its progress plans.
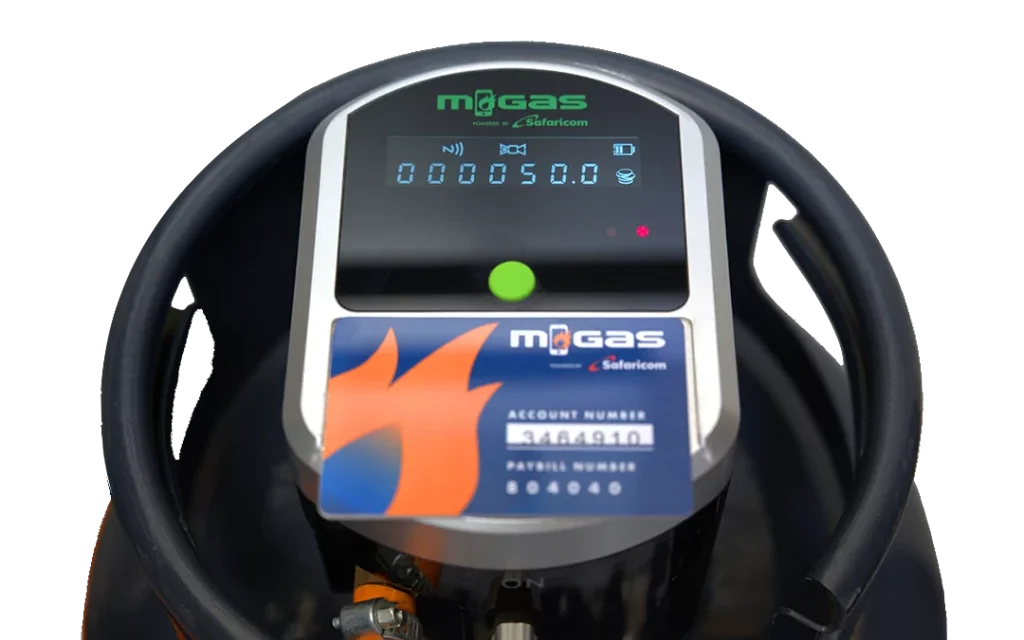
Carbon credit are central to the economics of fresh cooking companies resembling M-Gas. The firm provides LPG in small, inexpensive quantities with sensible meters so households pays as they prepare dinner. Revenue from the ensuing emissions reductions may also help help that mannequin. Koko Networks, one other Kenyan clean-cooking firm, entered administration after the federal government declined to authorise the carbon-credit gross sales on which its enterprise depended.
Circle Gas’s annual report says it obtained a “Letter of Acceptance” confirming that its carbon-credit initiatives met eligibility standards and will proceed to use for a “Letter of Authorisation.”
M-Gas introduced in January 2026 that its clean-cooking carbon venture had received a Letter of Approval. The report doesn’t make clear whether or not this is similar doc it calls a Letter of Acceptance.

Kenya’s carbon-market guidelines distinguish venture approval from authorisation to switch credit internationally. Under the related framework, the ultimate authorisation requires authorities approval and determines whether or not specified emissions reductions might be transferred overseas.
Circle Gas didn’t reply to a request for remark.
The worth of carbon credit
Circle Gas reported $67 million in contracted carbon credit but to be delivered as of the tip of 2025, and $57 million in money already obtained as prepayments in opposition to carbon-credit contracts. The first determine represents credit awaiting supply, whereas the second is cash patrons have already paid.
The accounts don’t disclose how a lot of the contracted portfolio is dependent upon the excellent authorisation or how a lot of the prepayments stays accessible.
Circle Gas says authorised credit can command considerably larger costs than credit bought upfront. It has not disclosed the anticipated premium. The firm additionally excludes the upper worth from its monetary projections, leaving the potential upside exterior its present funding assumptions.
Circle Gas grew income to $40.8 million in 2025 from $36.1 million, however remained loss-making, with a $39.3 million loss after tax. Its money reserves fell to $1.1 million, whereas internet liabilities climbed to $156.7 million from $116.5 million.
The firm says it wants about $28 million to fund its 2026 progress plans. Without extra funding, it expects to restrict funding and stay stagnant.
“At the date of approval of these financial statements, the additional third-party funding of approximately US$28.0m necessary to finance continued growth funding for the base case in 2026 is yet to be fully secured, and there is no certainty that funding will be available to the Group (Circle Gas),” the assertion stated.
The losses and funding wants can’t be attributed solely to the excellent authorisation. But the delay leaves a probably extra profitable supply of carbon income unsure as Circle Gas seeks new capital.
Koko’s carbon debt
Koko Networks constructed a enterprise promoting subsidised bioethanol stoves and gasoline to low-income households, counting on carbon-credit gross sales to cowl a part of its working prices. When the Kenyan authorities declined to authorise these gross sales, the corporate misplaced entry to a income stream it wanted to maintain the enterprise.
Koko shut down in January 2026, shedding greater than 700 workers. Its Kenyan and UK entities entered administration in February. The directors now face the duty of recovering cash owed to collectors, with the carbon credit held by its UK arm a central asset. Without a sale, FirstRand Bank is owed $60 million, whereas different unsecured collectors are owed about $171 million.
Koko’s collapse exhibits how a clean-cooking enterprise can accumulate substantial money owed when it can’t promote the carbon credit anticipated to fund its operations.
The government rejected Koko’s application in early February 2026, with Trade Cabinet Secretary Lee Kinyanjui saying the amount of credit sought may have exhausted Kenya’s allocation for worldwide transfers, leaving different initiatives in agriculture and manufacturing with little room to promote their credit overseas.
Unlike Koko Networks, Circle Gas has not had its authorisation request rejected. M-Gas introduced that its venture had obtained a Letter of Approval. However, Circle Gas’s accounts point out it’s nonetheless looking for a Letter of Authorisation and don’t disclose how a lot of its contracted carbon credit is dependent upon it.
Koko is the clearest warning of what’s at stake: carbon credit could also be recorded as belongings, contracted to patrons and used to safe financing, however they can not generate the anticipated money if the corporate can’t promote them.
Kenya’s carbon-credit guidelines give the federal government management over which emissions reductions might be bought overseas, leaving firms uncovered to selections that may have an effect on their revenues and money owed.
Circle Gas secured earlier approval for its venture however continues to be looking for authorisation, leaving the worth and supply of some contracted credit unsure.
True scale calls for shifting past surface-level integrations to strong execution. We’ve filtered the noise out of Moonshot 2026, optimising the convention strictly for high-calibre connections between startup founders, world monetary operators, enterprise leaders and people rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.